Preparing to Buy a First Home Without Draining Your Savings
Purchasing a home represents a major milestone for any household, bringing an exciting blend of fresh beginnings and practical decisions. Many prospective buyers spend months browsing local listings, imagining sunny living spaces, quiet home offices, and peaceful backyards. Yet balancing the excitement of buying property with the realities of upfront expenses and moving costs can easily feel overwhelming without an organized plan.
The key to enjoying this transition is approaching the journey with steady preparation rather than rushed urgency. Giving your household time to clarify genuine living priorities, review everyday finances, and safeguard emergency reserves turns home buying into an empowering project. With a thoughtful approach, you can step into homeownership with confidence and enduring comfort.
Clarifying What You Need in a Residential Property
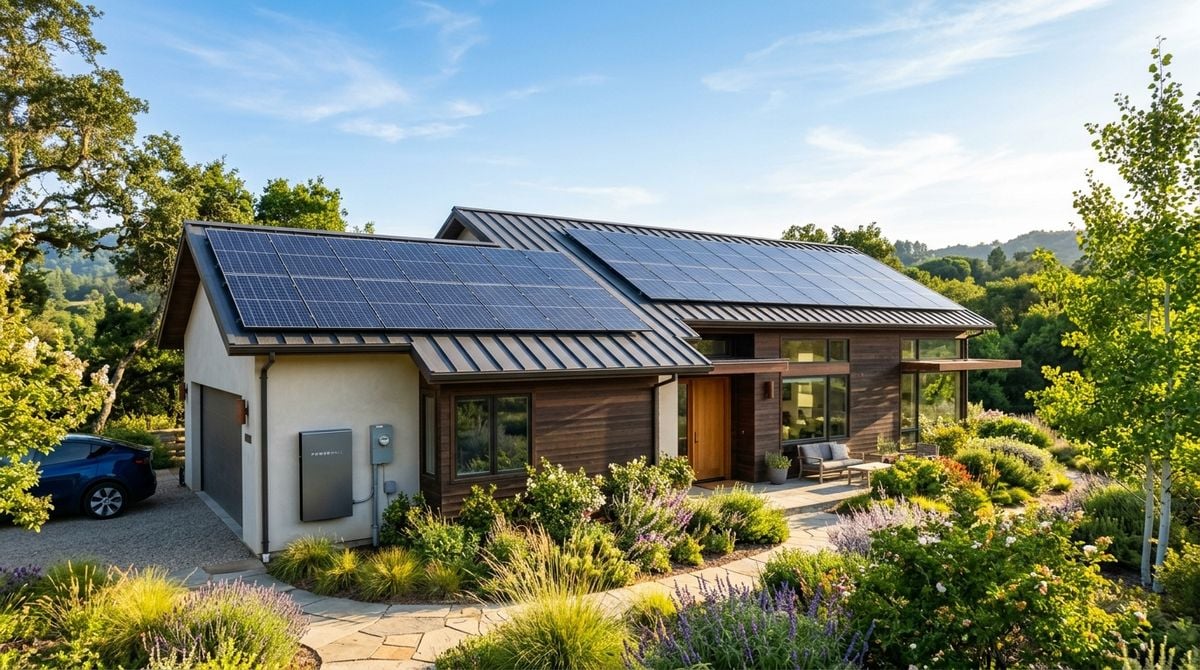
Before reviewing listings or comparing mortgage estimates, take time to evaluate how your household uses space every day. It is easy to be dazzled by expansive floor plans or modern decorative finishes, but excessive square footage often brings higher utility bills, additional maintenance chores, and furnishing pressures. Prioritizing functional features like practical storage, natural light, and manageable yard spaces ensures your home supports your actual lifestyle.
A home should serve as a peaceful sanctuary rather than an ongoing maintenance burden. Familiarizing yourself with different architectural styles, neighborhood layouts, and structural qualities helps you distinguish between fleeting cosmetic staging and durable construction. Evaluating traffic patterns, proximity to everyday amenities, and outdoor privacy further contributes to finding an environment where your family can truly settle down.
When exploring residential features and studying what makes a property truly comfortable, browsing dedicated real estate guides like cashbuffalo.org can provide helpful perspectives on architectural design and neighborhood qualities before you attend formal open houses. Having a grounded understanding of home features prevents impulsive decisions driven by temporary trends.
Balancing Cash Flow and Credit Obligations
Preparing for homeownership requires looking beyond a single down payment figure. Lenders examine your broader financial health, including consistent monthly income, existing balances, and overall debt commitments. Organizing your personal obligations well ahead of time places you in a far better position to manage mortgage payments alongside regular household expenses.
Reviewing personal loans, credit balances, and recurring obligations gives you a clear picture of your borrowing capacity. Paying down revolving balances or consolidating higher-rate debts frees up valuable breathing room within your monthly routine. This proactive adjustment ensures that utility bills, property upkeep, and home expenses do not strain your ongoing living standards.
Gaining insight into cash flow management and financing fundamentals is an essential step in this process. Informational platforms such as Dailipay.net offer useful guidance on balancing personal credit lines, loans, and everyday liquidity for long-term stability. Understanding how these financial components work together allows you to approach the borrowing process with calm assurance.
Protecting Your Emergency Cushion
A frequent error among first-time buyers is exhausting all available savings to maximize a down payment. While reducing your borrowing principal is helpful, leaving your bank account depleted creates unnecessary vulnerability. Unplanned maintenance needs, minor plumbing repairs, or appliance replacements can quickly turn moving week into a stressful ordeal if your safety reserve is gone.
Maintaining a dedicated emergency fund separate from your closing funds provides crucial peace of mind. Knowing you have an untouched safety buffer ensures that routine household surprises do not derail your overall finances. This protection allows your family to settle into the new property without constant worry about unexpected disruptions.
Protecting your savings routine during the buying journey is equally vital. Developing practical habits for managing unexpected family expenses on a structured budget ensures your purchase timeline stays on track when unplanned costs arise. By learning to handle sudden expenses through disciplined budgeting, you keep your savings intact for the move.
Practical Steps for the Months Before Moving
The journey toward closing day involves multiple practical tasks that become far simpler when broken into manageable steps. Tackling documentation, organization, and lifestyle adjustments early prevents last-minute chaos and keeps the entire household organized. Planning your calendar in advance provides room to handle unexpected scheduling conflicts, work obligations, and family commitments without feeling rushed.
- Collect recent bank statements, tax records, and proof of earnings into an orderly digital folder so lender documentation requests can be completed promptly.
- Review recurring subscriptions and household memberships, pausing services you rarely use to direct extra funds toward moving expenses.
- Visit prospective neighborhoods during different times of the week to observe traffic flow, pedestrian activity, and ambient noise levels before placing an offer.
- Draft an initial moving inventory that distinguishes between essential furniture and items that can be acquired gradually after settling into the property.
Focusing on these straightforward tasks provides tangible momentum throughout the transition. Dividing complex logistical goals into clear actions keeps stress low and gives your family quiet confidence as move-in day nears.
Establishing Sustainable Habits in Your New Home
The work of sustainable homeownership continues after the keys are in your hand. The early weeks often bring an urge to buy new furniture immediately, paint every room, or begin major landscaping overhauls. Resisting the temptation to remodel in a hurry protects your monthly budget and allows you to observe how the home truly functions across different seasons. Pacing your decorative projects also gives you financial breathing room as you adjust to your new baseline of household expenses.
Living in the home before making significant structural changes helps you discover what improvements are truly necessary. Natural lighting might alter your decorating ideas, or a simple furniture rearrangement might solve a storage issue without expensive contractor work. Giving your household time to adapt to utility costs and seasonal rhythms ensures your property remains an affordable sanctuary.
Building Long-Term Peace of Mind
At its heart, buying a home is about creating a stable setting where your family can thrive, recharge, and enjoy everyday moments together. When you pair deliberate property selection with careful financial planning and protected reserves, you replace moving stress with lasting security. Taking measured, sensible steps today establishes a foundation for comfortable, peaceful living in the years ahead.